Asia to add 700+ million middle-class adults by 2036 as e-commerce moves beyond cards, WDL and EBANX find
Joint study shows emerging markets will generate 60% of new online spending over the next decade — most of it from consumers without a credit card
SINGAPORE – Media OutReach Newswire – 21 October 2026 – Asia is projected to add 702 million middle-class adults between 2026 and 2036, three-quarters of all middle-class growth in emerging markets, according to a new study from World Data Lab (WDL) and EBANX, a global technology company specializing in payment services for emerging markets.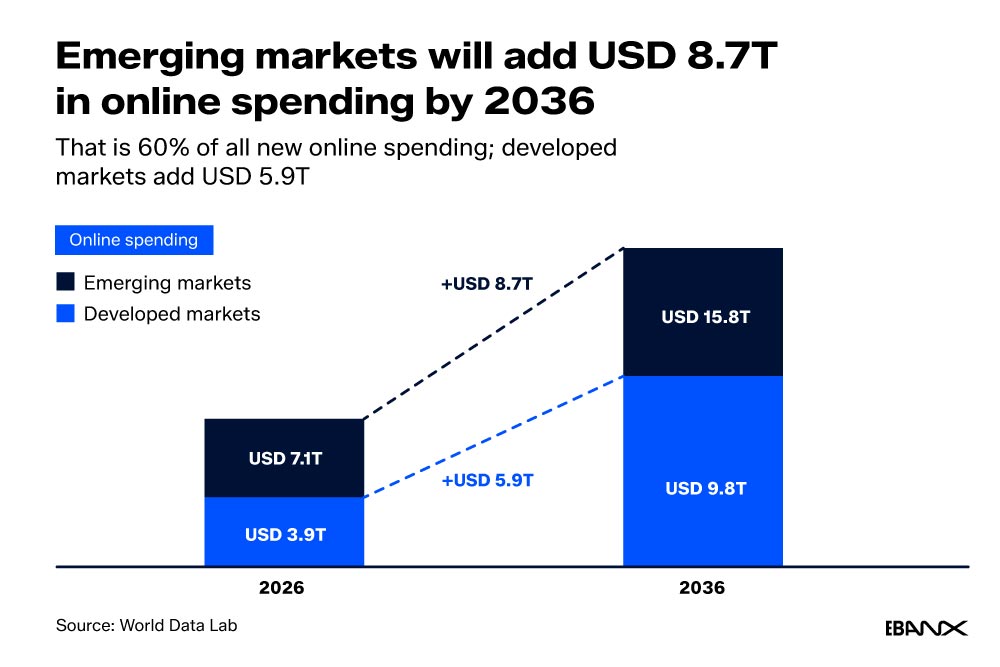
But this new consumer class will not shop the same way developed-market consumers do: by 2036, only 20% of adults in emerging markets will hold a credit card, against 66% in developed markets.
Global online spending is projected to grow from USD 11 trillion in 2026 to USD 25.6 trillion in 2036. Emerging markets add USD 8.7 trillion of that increase (60% of all new online spending), with China (USD +4.7 trillion) and India (USD +1.3 trillion) leading this growth. Indonesia (USD +243 billion), Brazil (USD +249 billion) and Mexico (USD +191 billion) form the next tier.
The categories matter as much as the markets. Online gaming spending in emerging markets grows 14% a year over the decade, the fastest of any category, and SaaS nearly 10%. Emerging markets will generate 76% of global growth in social media spending and 64% in SaaS.
The demographic picture challenges a common assumption. Consumers aged 45 and over account for 51% of emerging markets' online spending growth through 2036, and spending by those aged 65 and over grows 12% a year, faster than any other age group.
The outlook was discussed during "Navigating Payments: How innovation and fragmentation are changing the game for e-commerce," a webinar co-hosted by World Data Lab (WDL) and EBANX.
"Over the next ten years, people aged 45 and over will add USD 4.4 trillion in online spending in emerging markets, half of all the growth. Some of them already shop on their phones and will keep doing so as they get older. Others will buy online for the first time in their fifties or sixties. Merchants who build their checkout only for a 25-year-old will miss both groups," explained Wolfgang Fengler, CEO of WDL.
The study models consumer spending, demographics, and financial access across 184 countries to 2036, drawing on the World Bank's Global Findex and WDL's consumer models, combined with EBANX's experience processing payments for global merchants in emerging markets since 2012.
"If your checkout only takes credit cards, you are competing for one in five adults in emerging markets and conceding the other four", said Marie-Elise Droga, Chief Revenue Officer of EBANX. "The merchants growing fastest with us didn't wait for cards to arrive: they added the payment rails their customers already use, and they're taking new buyers, bigger baskets and recurring revenue that card-only competitors can't even see."
834 million new online buyers, 281 million new credit cards
Between 2026 and 2036, the global economy will add 834 million online buyers but only 281 million credit card holders—a ratio of nearly three to one. In emerging markets, two in three new online buyers (67%) will arrive without a credit card. Adults without it already account for 55% of online spending in emerging markets, a share that rises to 90% in India and 93% in Sub-Saharan Africa. Credit cardless adults also represent 52% to 59% of spending in every digital category, from gaming and SaaS to streaming and travel.
Digital payment use is also running ahead of online shopping. Of the 2.6 billion emerging-market adults spending between USD 6 and USD 25 a day, 70% already pay merchants digitally while only 33% buy online, leaving at least 957 million digitally active consumers who are not yet online buyers. Many hold a bank account or mobile wallet but no card that works at an international checkout.
"This is closely tied to the innovation that came out of the financial industry in emerging markets, which developed solutions for an increasingly mobile economy and for the habits of local consumers. Today, we call them local payment methods, or LPMs, and they allowed e-commerce growth to decouple from the credit card, which still has very low penetration in these countries," said Estelita Hass, head of Market Intelligence at EBANX.
Subscriptions are the next frontier — and India shows why
Recurring categories such as streaming, SaaS and online education will reach USD 2.1 trillion a year in emerging markets by 2036, with USD 1.1 trillion coming from adults without a credit card. In India, 82% of recurring online spending will be cardless. Account-based recurring rails are beginning to close that gap: a global SaaS company saw a 20% uplift in new subscribers after adding UPI at checkout in India, and cybersecurity company Nord Security now generates 28% of its revenue in Brazil through Pix Automático, Brazil's recurring instant payment, six months after launching it with EBANX.
The webinar presentation is available at [LINK].
Hashtag: #EBANX #WorldDataLab #Fintech #Payments #EmergingMarkets #Consumers
The issuer is solely responsible for the content of this announcement.
ABOUT EBANX
EBANX is the leading technology platform connecting global businesses to the world's fastest-growing digital markets. Founded in 2012 in Brazil, EBANX was built with a mission to expand access to international digital commerce. Leveraging proprietary technology, deep market expertise, and robust infrastructure, the platform enables global businesses to offer hundreds of local payment methods and streamline cross-border payments across Latin America, Africa, and Asia. With a global footprint, it established a technology and regulatory headquarters in Singapore in 2026. More than just payments, EBANX drives growth, enhances sales, and delivers seamless purchase experiences for businesses and end users alike.
For further information, please visit:
Website: https://ebanx.com/en/
LinkedIn: https://www.linkedin.com/company/ebanx/